Image © Adobe Images
The euro risks further losses this week as building Federal Reserve rate hike bets meet risks around the French budget and the ECB leadership change.
The euro-to-dollar exchange rate starts the week at 1.1014, its lowest since April 2025, after hot U.S. inflation figures sparked a dollar rally on expectations of further Federal Reserve rate hikes.
From a technical perspective, EUR/USD has broken out of the range marked by the orange lines on the chart:
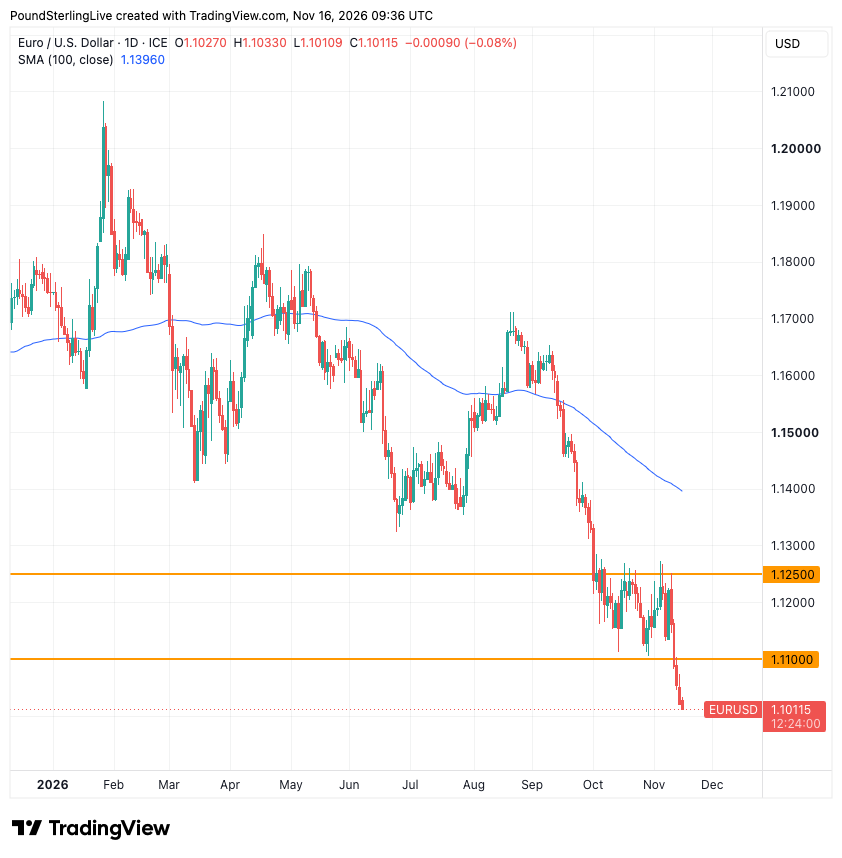
Above: EUR/USD at daily intervals with the 100-day moving average (blue) and the old 1.1100-1.1250 range (orange).
The pair traded between 1.1100 and 1.1250 from early October until a daily close at 1.1090 on 11 November, the day after the U.S. inflation data, broke the floor of that range.
Graphical horizontal resistance at 1.1100, the lower orange line, is old support turned resistance and now caps any rebound.
Below 1.10, Commonwealth Bank of Australia identifies the next support at 1.0809, the halfway point of the pair's five-year range, which it does not expect to be tested this week.
Pound Sterling Live sees a break below 1.10 as a real prospect this week, with 1.1100 capping any rebound.
A daily close back above 1.1100 would change the near-term Euro to Dollar forecast.
On a medium-term view, the 100-day moving average, the blue line, has been falling since September and sits well above the market, confirming a downtrend that has taken EUR/USD down from 1.1711 on 21 August.
Last week's Week Ahead Forecast looked for chop between 1.1100 and 1.1250, but the hot U.S. inflation report on 10 November sent the pair through the floor of that range a day later, and it has not closed above 1.1100 since.
The Dollar, Yields Surge on Heating Fed Rate Expectations
The dollar and U.S. bond yields rose last week after U.S. PPI inflation recorded a headline rate to 6.5% y/y on Friday, the highest level since November 2022. That followed Tuesday's U.S. consumer price release where the monthly inflation rate rose 0.4% in October against a 0.3% consensus, and core prices beat forecasts for a third consecutive month.
Money markets now price back-to-back quarter-point Fed hikes in December and January, which helped yields on two-year bonds jump back to near the year's highs:
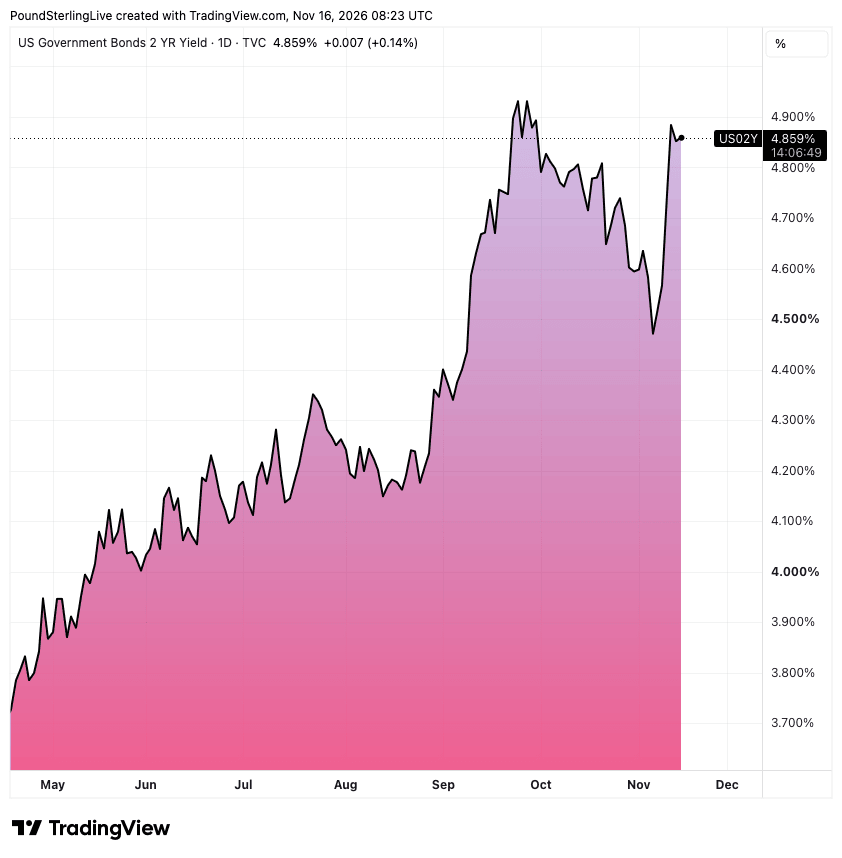
"Two-year USD swap rates have risen 35bp since the Federal Reserve's Christopher Waller mentioned a 50bp hike and core CPI overshot on 10 November, while other Fed speakers have done little to quell the hawkish repricing," says Francesco Pesole, FX Strategist at ING, in a new FX market analysis from the Dutch bank.
What does the gap between two-year swap rates tell us? It measures how much more investors earn on short-dated dollar interest rate contracts than on euro ones, so a wider gap makes the dollar more rewarding to hold.
That gap "has widened by nearly 35bp to its widest since September 2025," says ING, and adjusted for inflation expectations it is at its widest since December 2022.
U.S. Retail Sales and Fed Minutes Test the Dollar
U.S. retail sales for October are due at 13:30 UK time on Tuesday, with consensus looking for growth of 0.1% after 0.8% in September.
Under the playbook, sales above consensus would strengthen the dollar and push EUR/USD lower.
A miss would give the euro room to recover.
The minutes of the Fed's October meeting follow at 19:00 on Wednesday, and Commonwealth Bank of Australia expects them to be "hawkish, though not as hawkish as recent public comments from FOMC members."
Fed Chair Kevin Warsh and New York Fed President John Williams speak during the week, although ING expects "very little" from Warsh.
Société Générale expects dips in the dollar to attract buyers until U.S. inflation figures on 25 November settle the size of the Fed's December move.
Nvidia reports earnings and Anthropic makes its stock market debut this week, and "the larger risk of a USD correction comes from US equities, which have shown great potential to drive dovish repricing," says ING's Pesole.
Industrial production, housing starts and weekly jobless claims are second-tier releases.
The Euro Faces a French Budget Vote and De Cos Risk
France's parliament holds its vote on the government's 2027 budget on Tuesday, where defeat would add to the strain on French borrowing costs that has weighed on the euro since September, as Pound Sterling Live has reported.
"French risks have been a major headwind for the EUR since the end of September," says Lefteris Farmakis, a strategist at Barclays. "We continue to assess the risks for the EUR as skewed to the downside, as the essence of France's political impasse remains the same."
The EU Council meanwhile is set to choose a successor to ECB President Christine Lagarde, with Spain's Pablo Hernández de Cos and the Netherlands' Klaas Knot the leading candidates, "for EUR/USD, a return below 1.10 is not ruled out by the end of the week if the EU Council selects De Cos," says Société Générale.
"The Bank of Spain governor is considered a centrist with dovish leanings opposed to his more hawkishly inclined Dutch rival for the post," the French bank adds.
Eurozone negotiated wages for the third quarter on Friday, where consensus looks for 2.6% after 2.4%, are a second-tier release, as are speeches by Lagarde and ECB Chief Economist Philip Lane.
Commonwealth Bank of Australia expects the ECB to hike in December, but "with a 25bp December hike almost fully priced, any gains in EUR/USD will be limited."
Speculators hold the most stretched short position in the euro of any currency relative to its two-year range, according to MUFG, and because they must buy euros back to close those positions, a rebound can gather pace quickly if the dollar's momentum fades.
"We feel EUR/USD can hold the line at 1.100 this week, but risks of a break lower are significant, especially as that would be only a small stretch relative to short-term fundamentals," says ING's Pesole.
The pound has held its ground against the single currency, with the pound-to-euro exchange rate at 1.1979, and a further fall in EUR/USD would leave GBP/EUR better placed to clear 1.20.
Pound Sterling Live's Euro to Dollar forecast looks for a break below 1.10 this week if Fed officials and the minutes keep back-to-back hikes on the table, with 1.1100 capping any rebound.