Image © Adobe Images
The euro could fall further as markets price the chance the ECB is forced into supporting French debt.
The euro fell to 1.1161 against the dollar on Monday, its weakest since May 2025, after Spain's Pedro Sánchez called a snap general election for 29 November and the French spread over Germany re-widened to 147 basis points.
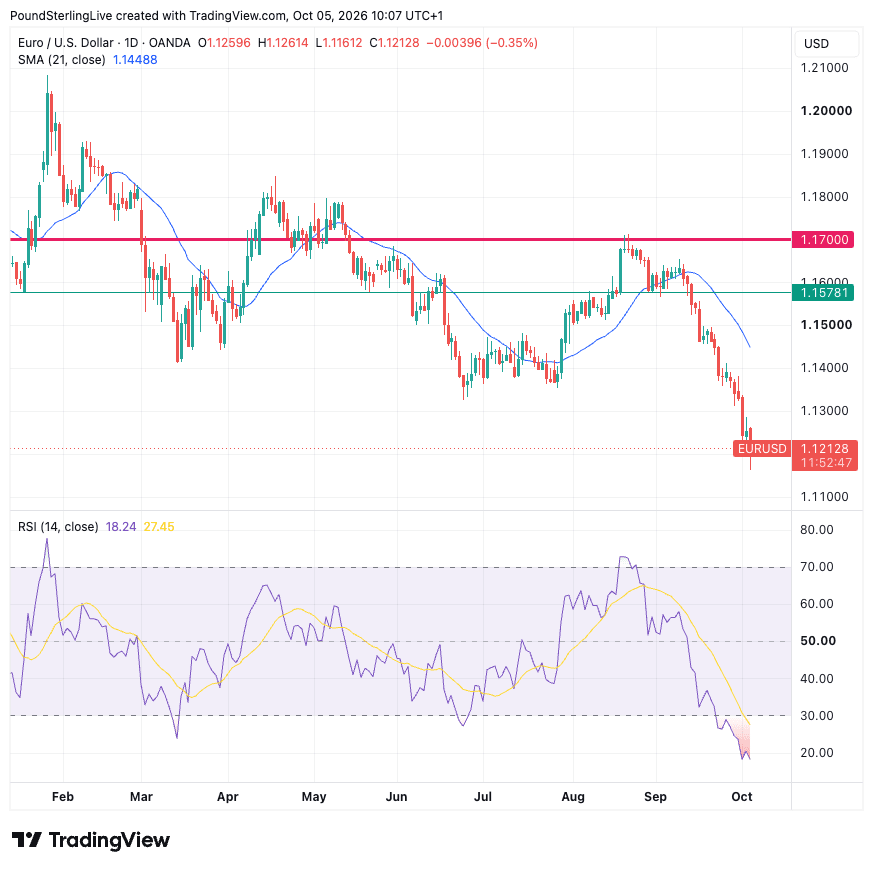
Chart courtesy of TradingView
The two developments are not of equal weight for the currency.
"Spain is a bit of a sideshow, but France is the real deal in terms of risk premia for the euro," says Neil Wilson, UK Investor Strategist at Saxo Markets.
Spanish ten-year spreads over Germany widened to 74bp on Friday, a fraction of the French equivalent.
What Spain adds is the perception that political risk is no longer contained to one member state, arriving in the same week French yields hit levels last seen in 2011.
France's budget proposal caps the deficit at 5% next year against 6.5% without action, and the bond market is not treating passage as given.
"The move in French bond yields and spreads shows the market does not have faith the government will carry out the required fiscal reform," says Wilson.
The timetable runs through the quarter, with the budget bills due to be filed at the National Assembly by 6 October and debate scheduled from 13 October, after which parliament has 70 days to pass the bill.
Wilson notes the market is also exacting a risk premium ahead of next year's presidential election, with odds on Marine Le Pen shortening amid civic unrest and the deteriorating fiscal position.
EUR/USD Technicals Help Drive the Selloff
Part of this morning's move is mechanical, because the euro broke a formation that had been building for months.
"We think that technical analysis, which represents an important trading tool in FX, has also played a strong role in the EUR-USD dive: the fall below the 1.15 level represented the break of the neckline of a bearish head & shoulders pattern visible on daily charts, with the 1.1289 area as a final target," says Roberto Mialich, FX Strategist at UniCredit Bank.
Daniella Arcadipane, Senior Currency Specialist at Indigo
Moving a life-changing sum abroad? You won’t be doing it alone.
One specialist explains every step in plain English and stays with it until the money lands. FCA authorised, FRN 594433.
Talk to a specialistWhat happened after that target was reached is the part that matters for the week ahead.
"Usually, when a target on charts is reached, profit taking follows. Hence, the genuine drop below 1.1289 suggests that investors still do not rule out riding a further decline of the euro, making a retest of 1.10 possible in the near term," says Mialich.
Mialich attributes that willingness to stay short to the political tensions in France and Spain and to fears of contagion across the European sovereign debt market.
Positioning backs him up, with CFTC data showing euro shorts rising to 7.4% of open interest.
Societe Generale sets that against the spring of last year, when the market was net long 10% of open interest and French spreads traded around 70bp, roughly half of today's level.
Speculative accounts have been buying digital options with six-month and one-year strikes near 1.06 and 1.07, according to the same research.
EUR/USD Selloff Risks an Overshoot
As the daily chart shows - see above - the Relative Strength Index in the lower panel is now in oversold territory.
It's therefore a case of too far, too fast and a correction becomes increasingly possible.
Note that for the RSI to correct, the pair merely needs to sit still, although a soft bounce can't be discounted.
For a more meaningful recovery, we would need to see fundamental concerns start to recede. "The big question is whether this is the start of a new euro sovereign crisis or whether markets have already overshot," says Jim Reid, a strategist at Deutsche Bank. "My bias is towards the latter."
"France's fiscal problem is real and has been building for years, but that is why the timing of the latest move is so interesting: there has been little genuinely new in the fundamentals," explains Reid.
The momentum picture is consistent with that reading, the daily RSI at 18 marking the most oversold the euro-to-dollar rate has been since February.
The safe asset at the centre of the euro has also held up.
"As long as investors have access to a euro-denominated safe asset, the current problems of the French government remain a problem for OATs rather than for the euro itself," says Thu Lan Nguyen, Head of FX and Commodity Research at Commerzbank.
Bunds have stayed outside the contagion that reached other member states late last week, and Nguyen says signs of it spilling into Germany would be the clear warning signal for the euro.
ECB Intervention Risks Build
The euro area has a mechanism for exactly this situation, and that is the source of the pressure on the currency.
"The euro area now has a mechanism in place to deal with sovereign debt crises. From an FX perspective, the problematic aspect is that the ECB plays a central role in this mechanism," says Nguyen.
In a worst case the ECB is caught between its mandate to preserve price stability and its responsibility to safeguard financial stability.
Until now the framework was credible enough that markets never expected it to be used, which is why the eurozone's political crises of recent years passed without the currency moving.
"The fact that the common currency is now coming under pressure suggests, on the one hand, that markets see a rising probability that the ECB may have to intervene after all. On the other hand, it indicates growing doubts that the tools specifically designed for such a scenario would be sufficient to contain the problem," says Nguyen.
The conclusion investors are drawing from that is what sells the euro.
"Markets appear increasingly concerned that the ECB could ultimately be forced into a more persistently accommodative monetary policy stance in order to ease pressure on long-term bond yields," says Nguyen.
Rate expectations are moving that way already, with markets pricing only a 15% to 20% chance of an ECB hike this month against December as the live meeting.
The currency's decline makes the bind worse, because a weaker euro raises imported inflation while energy costs are already elevated, and spot has moved well clear of the 1.16 technical assumption underpinning the ECB's 2026 to 2028 projections.
Societe Generale asks how long before ECB speakers come out publicly in support of the single currency to slow the pace of its decline.
Isabel Schnabel, Philip Lane and Joachim Nagel all speak on Monday.
EUR/USD and GBP/USD: The Dollar Is Passive Here
US payrolls rose 29,000 in September against a 90,000 consensus, and October Fed pricing has collapsed to almost nothing, which removes the rate story from this morning's dollar strength.
The cross evidence makes the point, with the pound-to-dollar rate down 0.08% at 1.3231 while the euro-to-dollar rate is down 0.35%.
Sterling is being bought as the alternative to the euro, not as a dollar trade, which has taken the euro-to-pound rate to the July low at 0.8455, or 1.1827 in pound-to-euro terms.
A break there opens 0.8405 and 0.8370, equivalent to 1.1898 and 1.1947 for pound buyers, while Societe Generale identifies failure to reclaim the 50-day average at 0.8565, or 1.1676, as the signal the pullback continues.
The Next Levels
Beneath the market, 1.1161 is this morning's low, with Societe Generale putting the next support at 1.1075 and Mialich's 1.10 the level the market is now testing the case for.
Above, 1.1260 caps the immediate recovery and 1.1289 is the reclaim level, being the head and shoulders target that broke this morning.
Only a move back through the 21-day moving average at 1.1449 would mark a change of trend.
US ISM services lands at 15:00 BST and a strong print would revive the Treasury selloff driving this move, while any sign from Schnabel, Lane or Nagel that the Governing Council is weighing its support tools would confirm what the market is now selling the euro on.
Daniella Arcadipane, Senior Currency Specialist at Indigo
Moving a life-changing sum abroad? You won’t be doing it alone.
One specialist explains every step in plain English and stays with it until the money lands. FCA authorised, FRN 594433.
Talk to a specialist