Image © Bank of England
Britain's labour market report was firm enough to allow pound sterling to keep an eye on surging borrowing costs.
The British pound faces two-way action against the euro and dollar amidst worrying rises in borrowing costs that see the cost the government borrows at rise to the highest levels in decades.
"The rise in interest rates is directly linked to the deteriorating situation in energy prices, a trend that only looks set to continue," says Marcus Widén, an analyst at SEB.
The surge in British bond yields - the measure of government borrowing - is linked to a combination of factors, but the recent surge is most tighly correlated to the rising cost of oil and gas following the deterioration in the Middle East conflict.
This means the pound isn't impacted in isolation, making for a diverse set of developments across the FX strip:
- The pound-to-euro trades higher at 1.1680, benefiting from a 0.25% gain on Monday.
- The pound-to-dollar rate trades lower at 1.3470, with Monday seeing a 0.20% drop and Tuesday adding to the losses by 0.22%.
- What the divergent fortunes of these two GBP exchange rates are telling us is that:
1) The euro is finding the going particularly difficult. The GBP/EUR gain on Monday reflects the sizeable fall in EUR/USD, which is linked to the surge in European gas prices. We have seen on a number of occasions since the war in the Middle East started that the euro is particularly sensitive to the conflict.
The Eurozone has a bigger industrial and manufacturing base than the UK does, meaning the surge in gas prices is particularly difficult.
"The rising price of gas has contributed to pushing up electricity prices in Europe," says Widén. "European gas prices are above EUR 80/MWh."
2) The dollar is benefiting because the U.S. is less exposed to the evolving global energy squeeze. The U.S. is a net exporter of oil and gas, meaning higher prices are supportive of the country's balance of payments.
There will also be some safe-haven flows that benefit the dollar as global investors take cover.
The Eye-watering Surge in Borrowing Costs
For now, the global nature of the rout in global bond markets means no single currency is being picked out for punishment, although we are wary of this status quo not being guaranteed to last.
A key risk to the GBP is that Britain's bond yields are rising faster than elsewhere, reflecting the premium investors demand for holding British debt. The British ten-year gilt rose to 5.439% on Monday, the highest since 2007, just beyond the 5.576% peak of 2007 and we scroll out to the 1998 high at 5.862%.
For mortgage holders, the key concern rests on the 5-year gilt, which tends to price mortgages; here borrowing costs have surged to 5.037%, the highest since 2011.
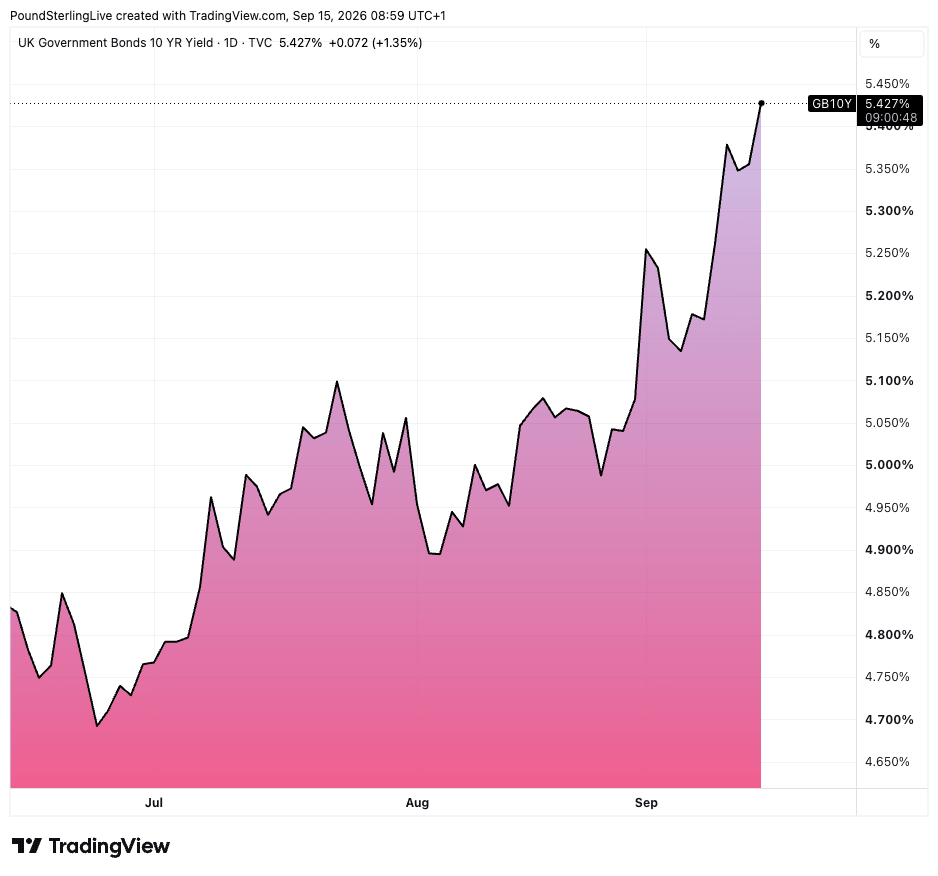
Above: GB 10-year yield surges on Tuesday morning.
The two-year bond yield is interesting as it is more of a reflection of Bank of England policy decisions: it rose to 5.013%, the highest since 2023. This move will reflect a surge in expectations that the Bank will raise rates on more than three occasions in the next 12 months.
"The recent gilt market movements seem to be intent on showing central banks they are out of time – the market is expecting action. UK government bonds are selling off, with shorter-dated gilts particularly hard hit. The UK is especially vulnerable because of the combination of oil prices at $100–110 a barrel and concerns about the credibility of the public finances ahead of the October 28 Budget," says Anthony Brinkman, High Yield Portfolio Manager at Principal Asset Management.
The Key Concern for Sterling is the Budget Impact
As long as nothing 'breaks' in the bond market and there's no UK-targeted buyers strike, GBP should continue to show mixed fortunes.
However, a headwind to any real outperformance is that the rise in borrowing means Andy Burnham's government has no room to play with in October's budget: any new spending commitments - of which has an abundance - will have to be funded by new taxes and borrowing.
That's a risky prospect for the Prime Minister, who might be tempted to push forward with some of his big-ticket spending commitments.
The window in which the Office for Budget Responsibility measures the bond market yields will start in early October, meaning there is still some hope that yields will retreat from recent highs and give him some spending headroom.
Pound Sterling Live's Expectation
Pound Sterling Live predicts that Burnham will consider that testing the bond markets is too politically risky, prompting him to opt for a low-risk budget that doesn't deliver any meaningful changes to the spending and borrowing trajectory.
He will instead opt for further gimmicky low-cost giveaways that will reflect well in the headlines but will be more or less neutral on the fiscus.
If so, the pound will avoid a major pitfall and can continue to benefit from the UK's robust economic fundamentals and elevated relative bond yields.
UK Jobs Data: Confirmation the Worst is Over, But No Smoking Gun for Bank of England
The UK economy was in focus on Tuesday, as labour market figures showed the deterioration of the past two years continues to fade.
Britain's unemployment rate holds steady at 4.9%, but there are still signs of weakness, with vacancies decreasing by 8K to 702K in the three months to August 2026.
Regular wage growth in the three months to July 2026 remained at 3.5%, excluding bonuses.
Including bonuses, the rate was 3.9%.
"Payrolls fall cements a hold from the MPC this week, but slack is building too slowly to prevent later rate hikes," says Rob Wood, Chief UK Economist at Pantheon Macroeconomics.
"Thursday is essential – if the Bank of England doesn’t hike and fails to communicate its long-term trajectory in a convincing manner, even 2-year yields at 5% may begin to look a little rich," says Brinkman.
If short-term yields fall faster than peers on the day, the pound would likely see some short-term pressures, although we suspect the global dynamic is increasingly more relevant to sterling than BoE policy at this point.
The Bank Consensus, Without the Terminal
The median, mean, highest and lowest from the October survey update, plus named point forecasts out to 2027.
Free information pack, issued by World Wide Currencies.