Image © Adobe Images
The Fed is set to hold but signal further hikes, keeping US yields bid and the pound capped against the dollar on Budget day.
The Pound to Dollar exchange rate is under pressure ahead of a Federal Reserve decision that is expected to deliver a hold on rates while warning that further hikes are coming.
A hawkish hold keeps US short-dated yields supported, which is the channel through which the dollar has drawn its strength this year, and the pair trades at 1.3288 as a result, back below the 1.3302 line that capped it through October and testing its 21-day moving average at 1.3282.
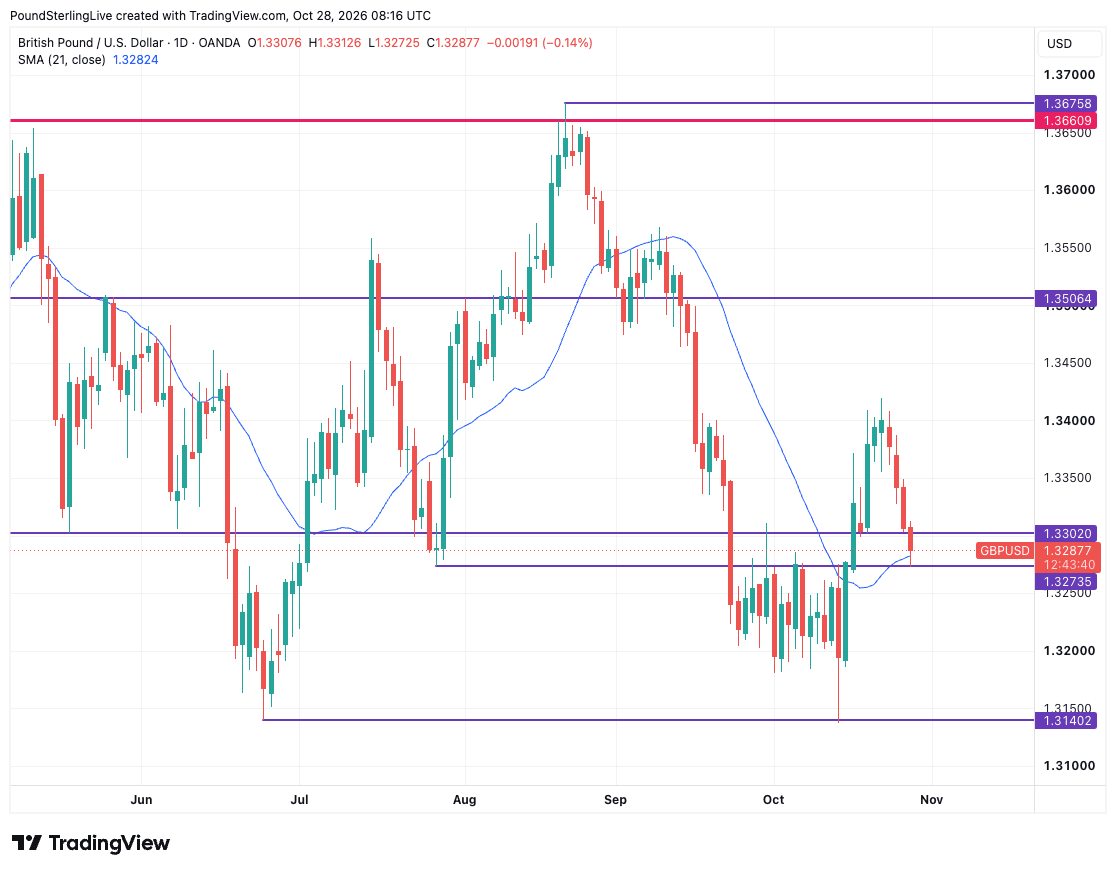
Above: GBP/USD at daily intervals, back below 1.3302 and testing the 21-day moving average.
Below the average sits 1.3274, the level the pair broke above on its mid-October recovery, which held at Tuesday's low of 1.3273; a daily close beneath it would put the 2026 low at 1.3140 back in view.
The outcome of the October Federal Reserve meeting will, of course, be key in determining how this plays out. The rule of thumb is that any strong steer towards further hikes will underpin the U.S. currency.
"Our economists expect the Fed to leave rates unchanged, and futures are pricing less than a 10% chance of a hike," says Deutsche Bank in a morning note.
"The broader message is likely to be hawkish: our economists think recent inflation data support the case for further tightening over time and foresee 50bp of further hikes across December and March," adds the bank.
Deutsche Bank expects Chair Kevin Warsh to make clear that tighter financial conditions are no substitute for rate hikes, which closes off the argument that higher bond yields have done the Fed's work for it.
BBVA expects the Fed to hold while keeping its tightening bias on display, "pairing the pause with a hawkish narrative as it seeks further evidence before deciding whether sticky inflation warrants lifting the fed funds rate beyond December," says the Spanish bank in its Fed preview.
The USD Bull-case: The Fed Hikes Today
Some houses say the Fed should go further: ANZ judges a hike is underpriced by the market, "recent inflation data have shown no clear progress towards the Fed's 2% inflation target and, in our view, warrant rate hikes at consecutive meetings," says the Australian bank.
Bank of America holds its call for a 25 basis point hike today, "though we acknowledge it would be a heavy lift given this week's price action," says the bank in its Global Macro Watch, adding that the case for further hikes stays intact unless something breaks.
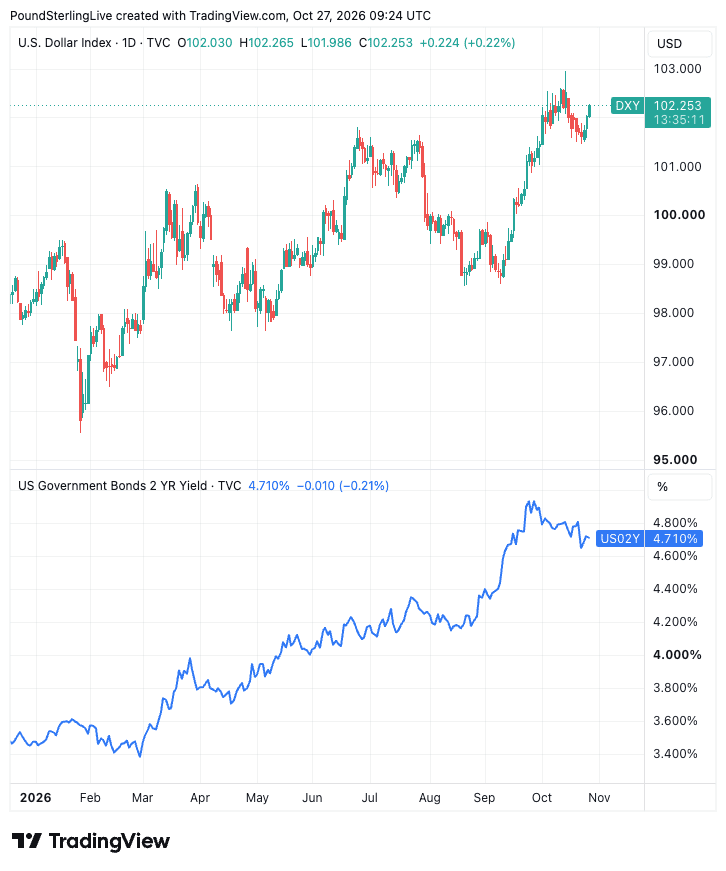
Above: The dollar index is carried higher by rising U.S. short-term bond yields (lower panel).
Should the Fed meet the market and hold, it's likely the press conference will help shape the dollar's reaction: "if the rhetoric remains hawkish, the USD is set to return on bid across the board, with UST yields soaring again," says UniCredit in its Fed preview, while a more relaxed Warsh would let forward curves price out tightening and give the other majors some relief.
Wells Fargo offers the dovish pushback, arguing gradual hikes make sense as a catch-up to a higher neutral rate rather than as a tool against supply-side inflation, and HSBC expects the Fed to deliver less tightening than the market prices.
Ahead of the decision, markets were served a reminder of why those tighter conditions can be sustained.
US Data Backs the Case for Higher Rates
U.S. Treasury yields edged higher on Tuesday, led by the two-year, and the 10-year rose to 5.00% before adding a further two basis points overnight, following a set of economic data that was on balance firmer than expected.
The Conference Board consumer confidence index rebounded sharply to 91.7 in October, reversing the decline it had suffered since June as energy prices rose.
Durable goods orders for September came in a touch below expectations at 1.8%, but new orders for computers and related products rose 3% on the month, taking annual growth to 26.7%, the fastest since 1997.
The computer orders figure is the AI investment cycle showing up in the hard data, and it is why the US economy keeps generating the demand that lifts inflation.
The enduring strength of the economy leaves the Fed little option but to consider higher rates, lest inflation continues to build and expectations slip the Fed's anchor.
Budget Day Adds the Pound's Own Risk
The Fed decides on the same day Chancellor John Healey delivers the Budget, which puts both sides of the pair in play before the London close (more).
Our house view is that the pound stays capped into the Budget and recovers in its wake, provided the Chancellor delivers no surprises on borrowing.
A clean Budget would clear the pound's own hurdle, but a Fed that signals December and March hikes keeps the dollar's rate advantage intact into year-end.
That leaves the 21-day average at 1.3282 as the line the pair must hold through both events, with a break of 1.3274 opening the way back towards the October range.