
Image © Adobe Images
The pound risks losing part of its rate support against the euro and dollar as inflation running below the Bank of England's forecast eases the case for a December hike, although a rising headline rate keeps further tightening on the table.
Pound sterling's support from Bank of England rate hike expectations has been trimmed by October inflation figures that showed the headline rate rising to 3.6% from 3.5%, in line with economists' expectations but below the Bank's own 3.73% forecast.
With inflation running below its own forecast, the Bank of England is under less pressure to raise interest rates again on 17 December, in turn trimming the yield advantage that has carried sterling to a 2026 high against the euro and limited its losses against a dollar lifted by Federal Reserve hike bets.
In the minutes following the release the pound-to-euro exchange rate dropped from a new 2026 high at 1.2015 to 1.20. The pound-to-dollar exchange rate fell from 1.3193 on the cusp of the release to 1.3172 in its wake.
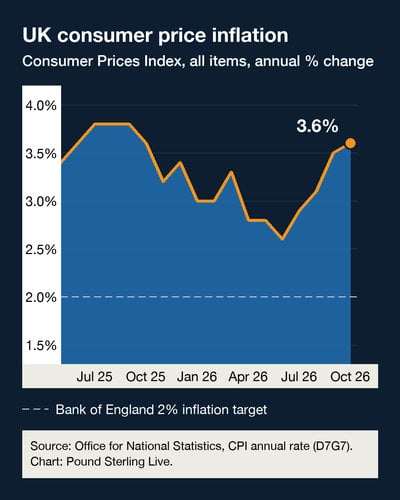
Services inflation, the Bank's gauge of domestically generated price pressure, held at 3.7%, a tenth below the 3.8% consensus, and core inflation was steady at 2.8%.
Goods drove the rise in the headline rate, with goods inflation climbing to 3.5% from 3.2% and motor fuels making the largest upward contribution, the ONS says.
As Pound Sterling Live has reported, the Bank can wait until February if October inflation undershoots its 3.73% forecast and services inflation holds at or below September's 3.7%.
October's figures met both conditions and a delay from December to February can take some near-term impetus out of sterling's upside against a host of G10 currencies.
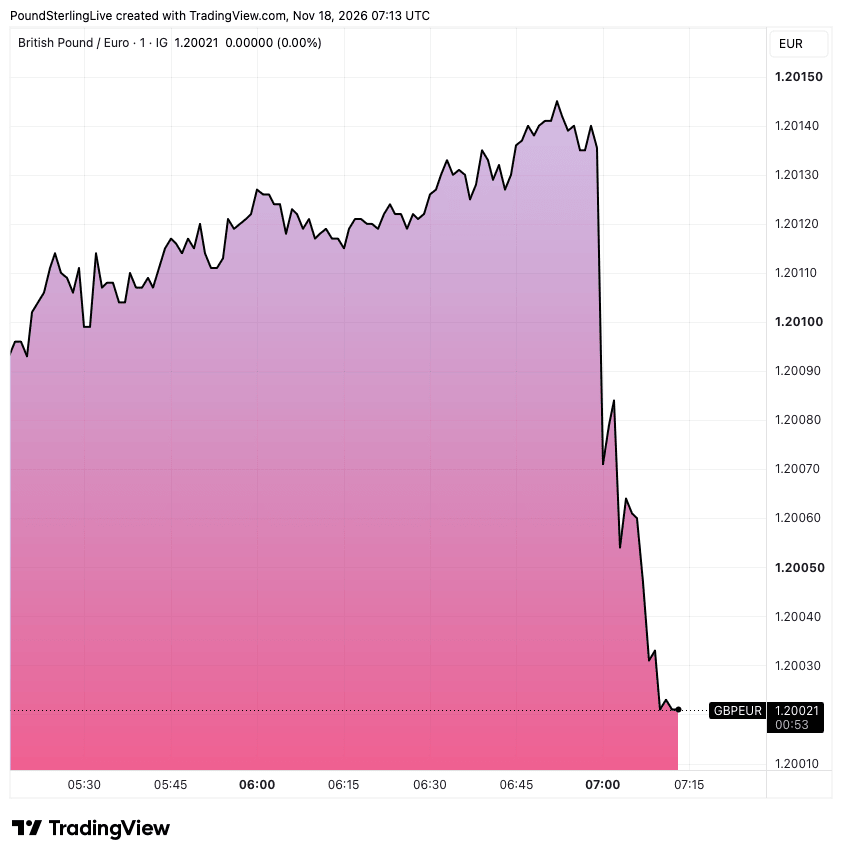
Above: GBPEUR in the minutes following the midweek release.
Inflation below the Bank's forecast supports the case made by Barclays ahead of the release that, "we continue to judge that the modal group on the MPC will prefer to hold Bank Rate at 4.0% in December if data comes in line with its expectation."
The figures also fell short of investment bank forecasts that sat at or above the Bank's: Goldman Sachs expected 3.7% with core at 2.9%, and Deutsche Bank 3.8%.
Pantheon Macroeconomics switched to forecasting a December hike on Tuesday, "absent a large downside surprise in the CPI data," says Rob Wood, Chief UK Economist at Pantheon Macroeconomics.
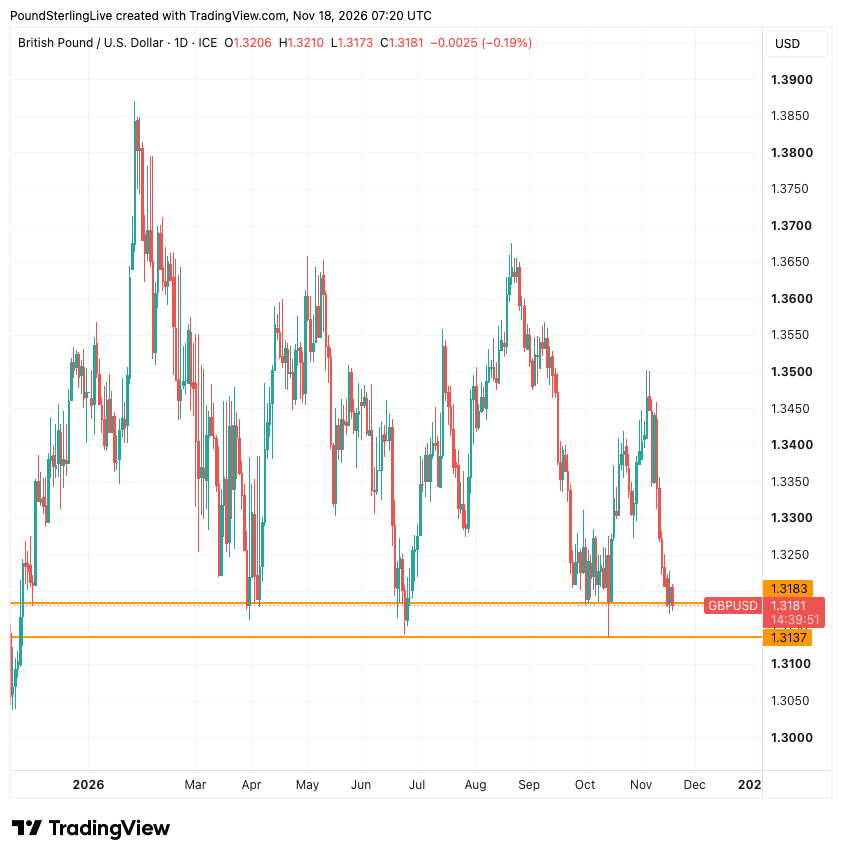
Above: GBPUSD is holding above a major multi-month tramline of support.
Money markets went into the release pricing around an 80% probability of a December hike. The pound is exposed to any reduction in that pricing against the euro, having rallied to a fresh 2026 high this week.
"Our positioning model G10 FX PIX 3.0 signals that GBP and CHF remain overbought," says Crédit Agricole.
Overbought positioning leaves the pound vulnerable to profit-taking, as investors holding crowded long positions sell to lock in gains when the news turns against them.
"The prospects for a resumption of the GBP rally vs the EUR could be limited, if UK rate markets struggle to price in an even more aggressive BoE tightening cycle from here," says the French investment bank.
Pound Sterling Live continues to hold a constructive medium-term view on the pound, with the Bank of England still raising rates as UK inflation proves sticky and slow to fall back to the 2.0% target.
The pound needs the Monetary Policy Committee to deliver a December hike to hold above 1.20 against the euro, with the 17 December decision the next test.