Image © Adobe Images
A French lender sets out the political outcomes that would put the single currency back on the front foot.
The euro can recover against the dollar under several outcomes from next year's French elections, according to new scenario analysis from Credit Agricole, the French investment bank and lender.
The analysis offers a counterweight to the anxiety that pushed the Euro to Dollar exchange rate to a 17-month low at 1.1154 and lifted the Pound to Euro rate to a 16-month high.
"Our results suggest that the EUR could recover under several scenarios including our baseline," says Valentin Marinov, Head of G10 FX Strategy at Credit Agricole, in a note dated 7 October.
Marinov runs the house's political scenarios through its EUR/USD fair value model, and Credit Agricole says the French fiscal and political outlook will remain a key driver of the euro for the next six to nine months.
France votes for a new president next April and May, and the start of this autumn's budget process triggered the latest sell-off in the euro and French government bonds.
Credit Agricole Watches Italy and Spain
Credit Agricole argues the euro's direction turns on whether French stress spreads into the wider eurozone government bond (EGB) market.
The debt-weighted gap between Italian and Spanish ten-year yields and German Bunds reached its widest in almost three years this month, and Marinov says that measure has been by far the stronger driver of the euro in recent years.
"We thus think that the EUR outlook would be driven more by the impact of the French political risks on the EGB market than the OAT market in isolation," he says.
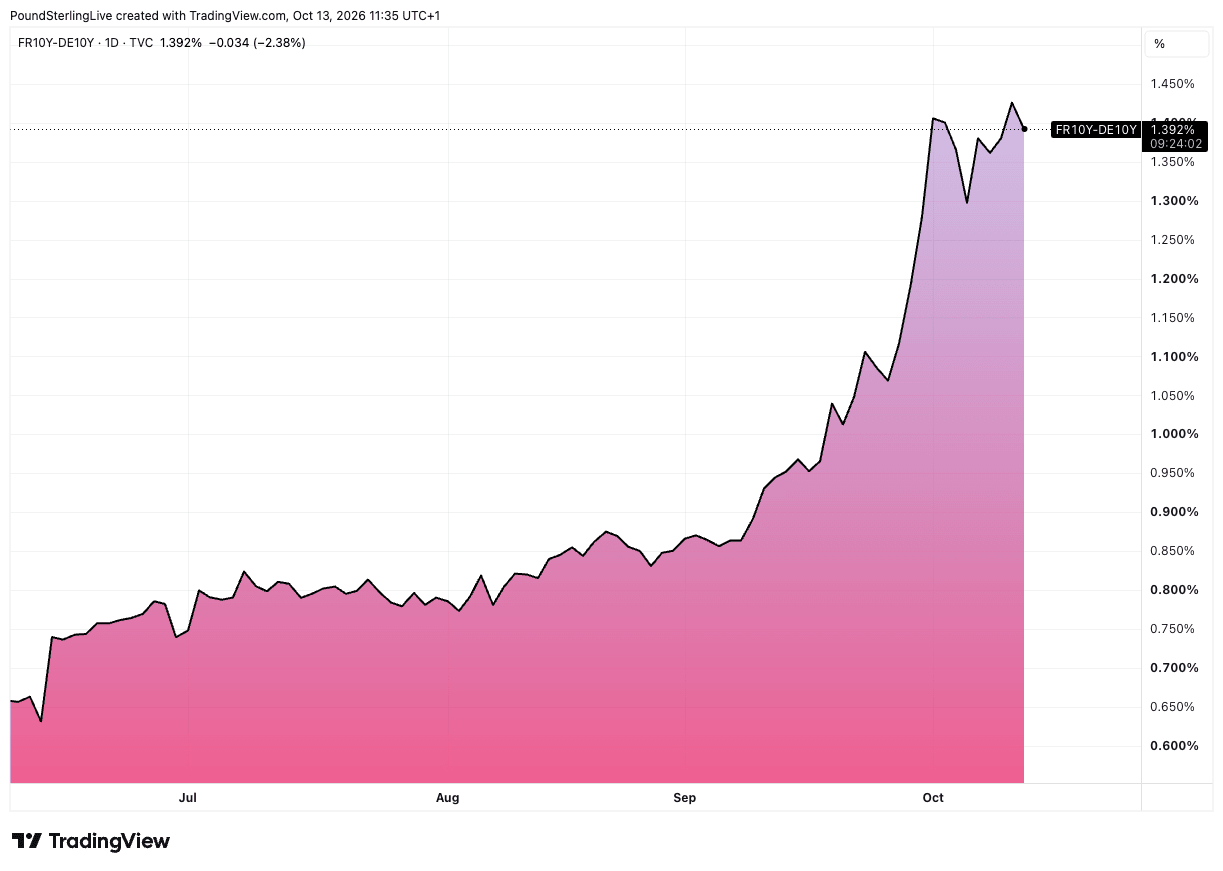
Above: French minus German ten-year bond yields: the spread that signals France-specific risk premium.
Contagion matters because tighter financial conditions can stop the European Central Bank (ECB) from raising interest rates, which is what happened in 2022, when wider peripheral spreads kept the ECB dovish and eroded the euro's rate appeal against the dollar.
Investors have pared back ECB rate hike expectations since French bonds sold off, but "the EUR-USD rate spread has dipped but has not collapsed," says Marinov.
Daniella Arcadipane, Senior Currency Specialist at Indigo
Moving a life-changing sum abroad? You won’t be doing it alone.
One specialist explains every step in plain English and stays with it until the money lands. FCA authorised, FRN 594433.
Talk to a specialistCredit Agricole gives three reasons it doubts a repeat of the 2022 sell-off:
• The eurozone economy shows considerable resilience, supported by robust domestic demand.
• It remains to be seen whether contagion from the French bond sell-off intensifies significantly further.
• The ECB is focused on containing inflation, and its hikes support the euro's rate appeal.
Investment bank analysts broadly expect the ECB to raise rates again in December.
"We forecast the ECB to raise rates in December this year and March next year, bringing the depo rate to 3.00% by March 2027," says a note from Nomura dated 7 October.
The French Outcomes That Lift the Euro
Credit Agricole condenses eight French political outcomes into five scenarios, ranked from most to least favourable for the euro:
1. Positive: a centrist president with either a centrist majority in the National Assembly or a technocrat government.
2. Baseline: a National Rally (RN) president with a centrist majority, or a centrist president with an RN majority in the National Assembly.
3. Adverse: an absolute majority for either RN or the Left.
4. Adverse: a hung parliament and policy paralysis.
5. Very adverse: a hung parliament with a runaway deficit.
In the positive and baseline cases, French, Italian and Spanish spreads to Bunds tighten notably, and Credit Agricole's model translates that into a stronger euro.
Under the positive scenario, the debt-weighted spread of French, Italian and Spanish bonds over Bunds narrows to between 77 and 88 basis points by the end of 2027.
Credit Agricole also finds that a hung parliament or absolute majority involving RN would do less damage to bond markets than the same outcomes involving parties of the left.
Near-term Recovery Signals
Credit Agricole's positioning model flagged the euro as oversold on 12 October, following a similar call from Helaba last week.
"At present, our G10 FX PIX 3.0 model signals that the EUR and GBP are oversold. Subsequently, we have entered longs in EUR/USD and GBP/USD with a take-profit of +4% and a stop-loss of -2%," says Credit Agricole.
Speculators hold their largest bet against the euro in more than six years, which leaves room for a sharp rebound if French news improves.
"EUR net shorts have increased further to their highest level since February of 2020, at almost 100,000 contracts," says Rabobank's weekly positioning review of 12 October.
Natixis says the level of French borrowing costs matters most, and the ten-year yield sits just below the threshold that triggered the last bout of stress.
"With the 10-year OAT still 15bp below the symbolic 5% mark (which had triggered the rally and the narrowing of the spread that pushed it back from 160bp vs Bund), the risk of a sharp rise remains contained," says Natixis in a 12 October note.
The Case Against a Euro Recovery
Credit Agricole's own economists warn the French budget arithmetic is deteriorating, estimating in a 6 October note that the 2027 deficit lands closer to 5.2% of GDP than the government's 5.0% target, even if parliament passes both bills unchanged.
"The snowball effect is gaining speed: debt crossed 119% of GDP in June and will breach 122% even under the most optimistic budget scenario. The arithmetic is unforgiving and the window to act is shrinking fast," says Credit Agricole.
The French government faces a possible vote of no confidence as parliament debates the budget.
"A vote of no confidence would further delay budgetary reform, generate additional uncertainty and put upward pressure on French bond yields," says Commonwealth Bank of Australia in a 12 October note.
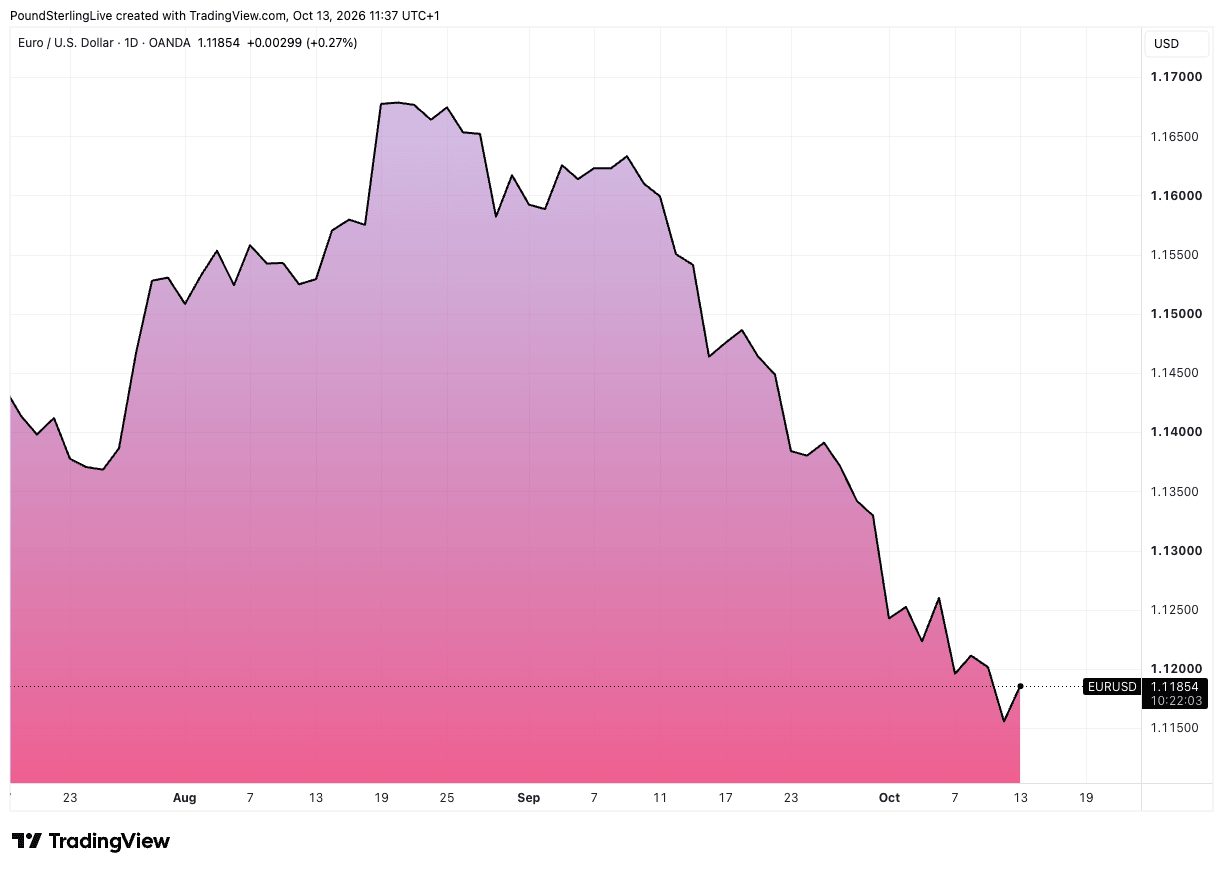
ING expects EUR/USD to stay in a 1.10 to 1.15 range over the coming months, squeezed between a hawkish Federal Reserve and French politics.
"Were French debt to suffer heavier losses than we are expecting, and the ECB be forced to abandon rate hikes, stop quantitative tightening or, in extreme circumstances, buy debt again, the euro's downside would be far greater," says ING in its October FX Talking publication.
OCBC sees any near-term euro bounce as limited.
"French fiscal fears may be off the boil, but not off the table. EURUSD may stabilise, yet unresolved budget risks and weak fundamentals suggest any rally is more relief, not a trend reversal," says OCBC in its 12 October weekly.
UOB on 13 October lowered its EUR/USD forecasts to 1.12 for the fourth quarter and 1.10 by mid-2027, citing a widening rate differential with the US.
EUR/USD Scenario Targets
Credit Agricole's scenario targets for EUR/USD, at the end of the third and fourth quarters of 2027:
• Positive: 1.17, then 1.19
• Baseline: 1.14, then 1.17
• Adverse: 1.12, then 1.14
• Adverse with policy paralysis: 1.08, then 1.09
• Very adverse: 1.06, then 1.05
Three of the five scenarios leave EUR/USD above today's 1.1154 by the end of 2027, with the baseline 1.17 sitting around 5% above spot.
The very adverse outcome implies a further fall of around 6% from current levels.
Over the near term, Credit Agricole expects EUR/USD at 1.13 in three months.
"In summary, we are cautious on the EUR from current levels but doubt that a repeat of the aggressive 2022 sell-off is on the cards," says Marinov.
What It Means for GBP/EUR
A euro recovery driven by French improvement would pull the Pound to Euro rate back from its 16-month high.
Credit Agricole's separate fair value model, updated on 12 October, judges EUR/GBP at 0.8464 to be "a bit undervalued" against a fair value of 0.8521, equivalent to GBP/EUR at 1.1815 against fair value at 1.1736.
ING takes the other side, preferring the pound in the G10 space on expectations that the Bank of England will hike rates.
"Aside from the dollar, we like the pound in the G10 space; it looks like the Bank of England will have to hike after all, and warmer UK-EU relations could see sterling rewarded," says ING.
Our house view is that the pound stays capped into the 28 October Budget and recovers afterwards, leaving any euro rebound on French news as a window for euro buyers.
Wednesday's US inflation data sets the dollar side of the trade, and the French ten-year yield's distance from 5% sets the euro side: a hold below that line keeps Credit Agricole's 1.17 baseline in view for EUR/USD.
Daniella Arcadipane, Senior Currency Specialist at Indigo
Moving a life-changing sum abroad? You won’t be doing it alone.
One specialist explains every step in plain English and stays with it until the money lands. FCA authorised, FRN 594433.
Talk to a specialist