Image © Adobe Images
Sterling's rally against the euro has reached momentum extremes with no precedent since the financial crisis, and a market pricing a series of Bank of England hikes leaves it exposed to a repricing.
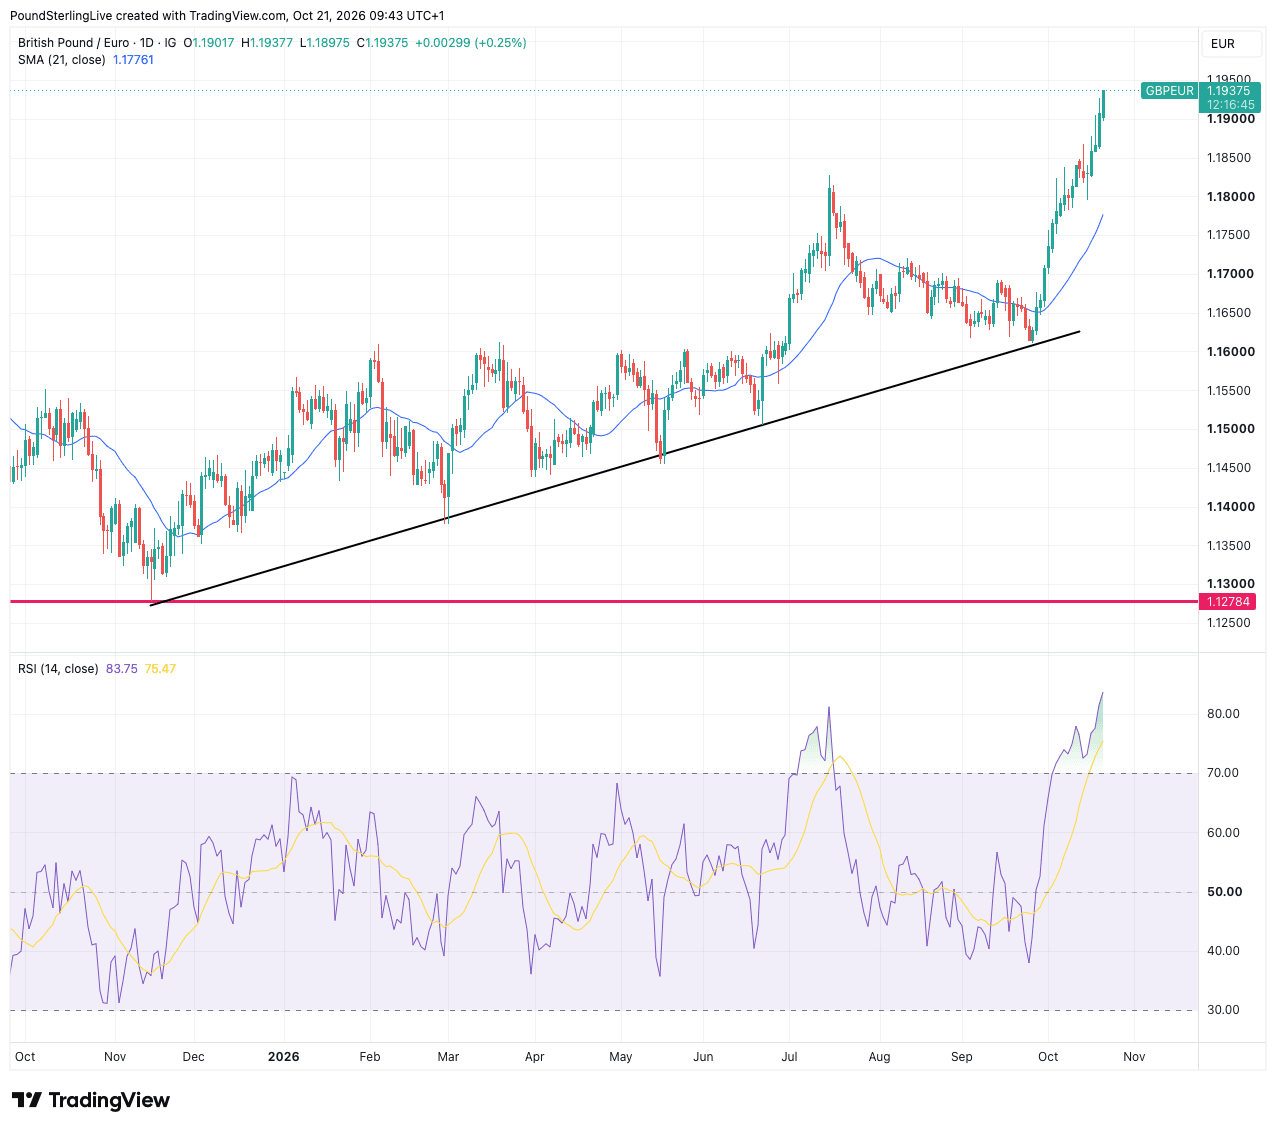
The Pound to Euro exchange rate is more overbought than at any point in Pound Sterling Live's records, which run back to the financial crisis, after two days of above-consensus UK data pushed it to fresh 17-month highs.
The pair trades at 1.1933, having reached 1.1938 on Wednesday, with the Relative Strength Index (RSI), a momentum gauge where readings above 70 mark an overbought market, at 84.
That reading tops the July peak near 81, the previous high in a dataset stretching back to 2008, and sits above every episode of the eurozone debt crisis, the Brexit referendum and the pandemic.
Spot sits 1.3% above its 21-day moving average at 1.1776, and our in-house modelling says a gap of this size must close through a pullback or a period of consolidation.
The pound's gains rest on a market pricing a series of hikes into 2027, and the analyst community is less convinced than the market that the Bank delivers them.
Wednesday's inflation beat, with CPI at 3.5% against a 3.4% consensus, fuelling sterling's rally against the euro and recovery against the dollar.
"We agree with current pricing for a high chance of a BoE interest rate increase at its next meeting in November. However, unlike the market, we do not expect a series of interest rate hikes," says Joseph Capurso, Head of International Economics at Commonwealth Bank of Australia.
"The swaps curve implies 95% odds of a November BOE rate hike and 100bps of tightening in the next twelve months," says a daily note from Brown Brothers Harriman, which argues the Bank will not need to tighten that far because the economy is operating below capacity and fiscal policy will likely turn more restrictive after the Budget.
OCBC's Sim Moh Siong says sterling has near-term support from resilient UK data and Bank of England tightening expectations, but the bar for further gains is rising.
"Aggressive rate pricing and looming Budget risks argue against chasing GBP higher," he says.
A repricing towards fewer hikes therefore looks to be the main headwind to the rally.
Stretched Rally Offers a Tactical Selling Opportunity
With the record stretched reading in the daily chart's RSI, the prospect of a pullback becomes increasingly likely and we see decent risk-reward in selling from these levels.
"With sterling positioning now stretched, there is room for a sharp downside move should Healey announce measures that damage growth without delivering a credible path to fiscal sustainability," says Matthew Ryan, Head of Market Strategy at Ebury.
Tactical short positions on sterling, particularly on the pound-euro cross, look increasingly attractive as a result.
The Euro Offers No Rescue
A pullback in GBP/EUR likely also needs a euro bid, yet the single currency's own problems argue against one.
The gap between French and German ten-year borrowing costs, the favoured measure of French stress, closed at 148 basis points on Monday, its widest since 2012, after a weekend of violent protests across France.
"The euro has enough problems to remain one of Europe's weakest currencies, and once positioning has settled down, it has a chance of ending up the weakest of the G10 currencies this year," says Kit Juckes, Chief FX Strategist at Societe Generale.
Bank of America says euro downside is best expressed on the crosses, and that of the major inflation markets the UK now stands out on real yields, particularly at the long end.
Crowded euro shorts are the one thing holding the single currency up, with Juckes noting the FX market has failed to react to the French spread widening to anything like the degree the bond market has.
Daniella Arcadipane, Senior Currency Specialist at Indigo
Moving a life-changing sum abroad? You won’t be doing it alone.
One specialist explains every step in plain English and stays with it until the money lands. FCA authorised, FRN 594433.
Talk to a specialistConsolidation Over Pullback, Budget Risks Deeper Pullback
Monday's week ahead forecast looked for the pound-to-euro rate to unwind from overbought conditions, and warned that above-consensus data would keep that pullback at bay.
Two beats in two days have held the pullback off, and the faded reaction to the second suggests the data-driven leg of the rally is complete.
A consolidation near current levels is now the base case, with the rising 21-day average closing the gap from below while the data keeps sterling bid and the euro stays friendless.
Friday's retail sales and PMI figures are the final tests before the Budget, and a hold above 1.19 through them would set the pound-to-euro rate up to challenge 1.20 once the Budget passes without incident.
A daily close below 1.19 would mark the start of the pullback route instead, with the 21-day average at 1.1776 the first target.
However, a trigger to a more meaningful pullback rests with the upcoming budget. Should Chancellor Healey misstep next week, a deep selloff in sterling will follow.